What Flood Zones Mean for Your Florida Insurance Coverage
If you live in Florida, flood zones are something you can’t afford to ignore. Whether you’re planning to buy property, already own a home, or just want to understand your insurance better, knowing what flood zone you’re in can impact everything from monthly costs to how much coverage you can get. Some areas flood more easily than others, and insurance companies base part of your risk and rate on this. So, if you’re thinking flood zones only concern people who live near the coast, it might surprise you how far inland these risk zones can stretch.
Knowing your flood zone isn’t just helpful. It’s often necessary when it comes to insurance decisions. Many lenders require flood insurance in certain zones, and it isn’t automatically included in a regular policy. The good news is, with the right information, you can make smart choices to keep your property protected and avoid headaches down the road. Let’s take a look at what these zones really mean and how they affect Florida flood insurance.
What Are Flood Zones?
Flood zones are parts of the map that help show how likely an area is to flood. These zones are created by FEMA and are used across the U.S. Each zone is based on factors like elevation, rainfall, storm surge, and how close a property is to water. FEMA divides them into different categories and labels them with letters such as A, AE, VE, and X. These labels give clues about the risk level, which is important when figuring out your flood insurance needs.
Here are a few key types of flood zones you might see in Florida:
– Zone A and AE – These are high-risk areas. If your home sits in one of these zones, getting flood insurance is usually required if you have a mortgage from a federally regulated lender.
– Zone VE – These are also high-risk but specific to coastal areas, where storm surge could be strong. These zones come with stricter building and insurance rules.
– Zone X (shaded) – These zones have moderate risk. Flooding could happen, but it’s less likely than in high-risk zones.
– Zone X (unshaded) – These are considered low-risk, but that doesn’t mean flood-free. Heavy rain and storms can still cause flooding here.
Flood zones don’t just show who needs insurance. They also help insurance companies figure out how much risk they’re taking when covering a property. A house in Zone AE will likely have different pricing and policy terms than one in Zone X. That’s why knowing your zone can make a big difference when looking at costs and coverage options.
How Flood Zones Impact Your Florida Flood Insurance
Flood insurance in Florida is closely tied to these zone maps. Your zone helps decide what kind of policy you’ll need and how much you’ll probably pay. If your property is in a high-risk zone, your lender may not approve your mortgage unless you have flood coverage. Even in low or moderate-risk areas, some people choose to get flood insurance as extra protection.
Rates and policy rules can vary depending on several details, such as:
– Your zone classification (A, AE, VE, etc.)
– How high your home sits above sea level
– If your property has flooded before
– The way your home is built, including the type of foundation
– How close you are to lakes, rivers, canals, or the ocean
For example, take two homes only a few blocks apart in the same neighborhood. One is just inside an AE zone, the other in a shaded X zone. Even though both homes could look the same in size and value, the one in AE will likely have a higher premium. The owner might also need an elevation certificate to help determine costs.
Knowing how these zones affect your insurance helps you plan better and talk more confidently with your insurance agent. It lets you make smarter choices and understand what you’re signing up for when you get flood insurance in Florida.
Navigating Flood Insurance Requirements in Florida
Living in Florida means being familiar with flood insurance rules. Not everyone is required to have it, but if your home is in a high-risk zone and your mortgage is through a federally backed lender, coverage is non-negotiable. Before closing, your lender will ask for proof of flood insurance and expect you to keep the policy active for the life of the loan.
Even if your home is in a lower-risk area, many Florida homeowners still buy flood insurance for peace of mind. Regular policies usually don’t include flood protection, and hurricane season can change things in a hurry. It’s a good idea to find out if your mortgage company has special flood insurance rules and to keep an eye on FEMA’s updated flood maps to see if your zone changes.
Here are a few steps you can take to stay ahead:
– Ask your lender if your flood zone means you need insurance
– Check for updates in your FEMA zone designation every few years
– Act quickly if your area has been rezoned to high-risk status
– Learn local Florida rules if you’re building or raising a structure
– Talk to a licensed agent who knows Florida zones and policies
Timing can be everything. Most policies don’t start right away. They often have a waiting period before coverage kicks in, so it’s better to act early—well before the next storm is on the forecast.
Steps to Take if Your Property Is in a High-Risk Flood Zone
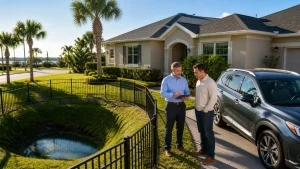
If you learn your property sits in a high-risk zone like AE or VE, don’t panic. You’re not alone, and there are smart actions you can take now to make your home safer and keep your insurance costs in check.
Here are a few helpful things to think about:
- Get an elevation certificate
This shows how high your house is compared to the flood level set for your area. If your elevation is better than average, it could help lower your premium.
1. Invest in flood-resistant upgrades
Raising your HVAC units, electrical outlets, or maybe even your whole home might reduce future damage and improve your insurance options.
2. Improve outside drainage
Keep gutters clear and shape your yard in a way that helps steer water away from the foundation.
3. Store documents and valuables above flood level
It’s always smart to keep important items high up, just in case flooding does happen.
4. Know your evacuation route
Learn your area’s evacuation plan and prepare a basic emergency kit. Have a place in mind where you can go if you need to leave quickly.
Different properties will need different steps, but starting now puts you in a better spot before heavy rain season arrives. Taking these steps also helps you build trust and clarity when working with your insurance provider.
Protecting Your Home and Peace of Mind
Flood zones impact more than just maps. They play a big role in what kind of Florida flood insurance you need, how much you’ll pay, and how to prepare for storms. Whether your property is at high or low risk, knowing your zone helps you stay informed and ready.
Being proactive means fewer surprises when the next weather event shows up. Florida’s property rules and FEMA’s maps change over time, so checking your flood status regularly and reviewing your coverage is worth the effort. Taking early steps now could save you time, money, and stress later on. Keeping your home protected with the right insurance gives you a little more confidence—especially when the skies start to darken.
Understanding your flood insurance options can seem tricky, but it’s a lot easier with the right support. Whether you’re in a high-risk area or just want extra protection against flooding, having the right insurance can make all the difference. For more help with selecting the best coverage for your needs, learn more about Florida flood insurance to see how Florida West Insurance can offer reliable solutions suited to your specific location.